
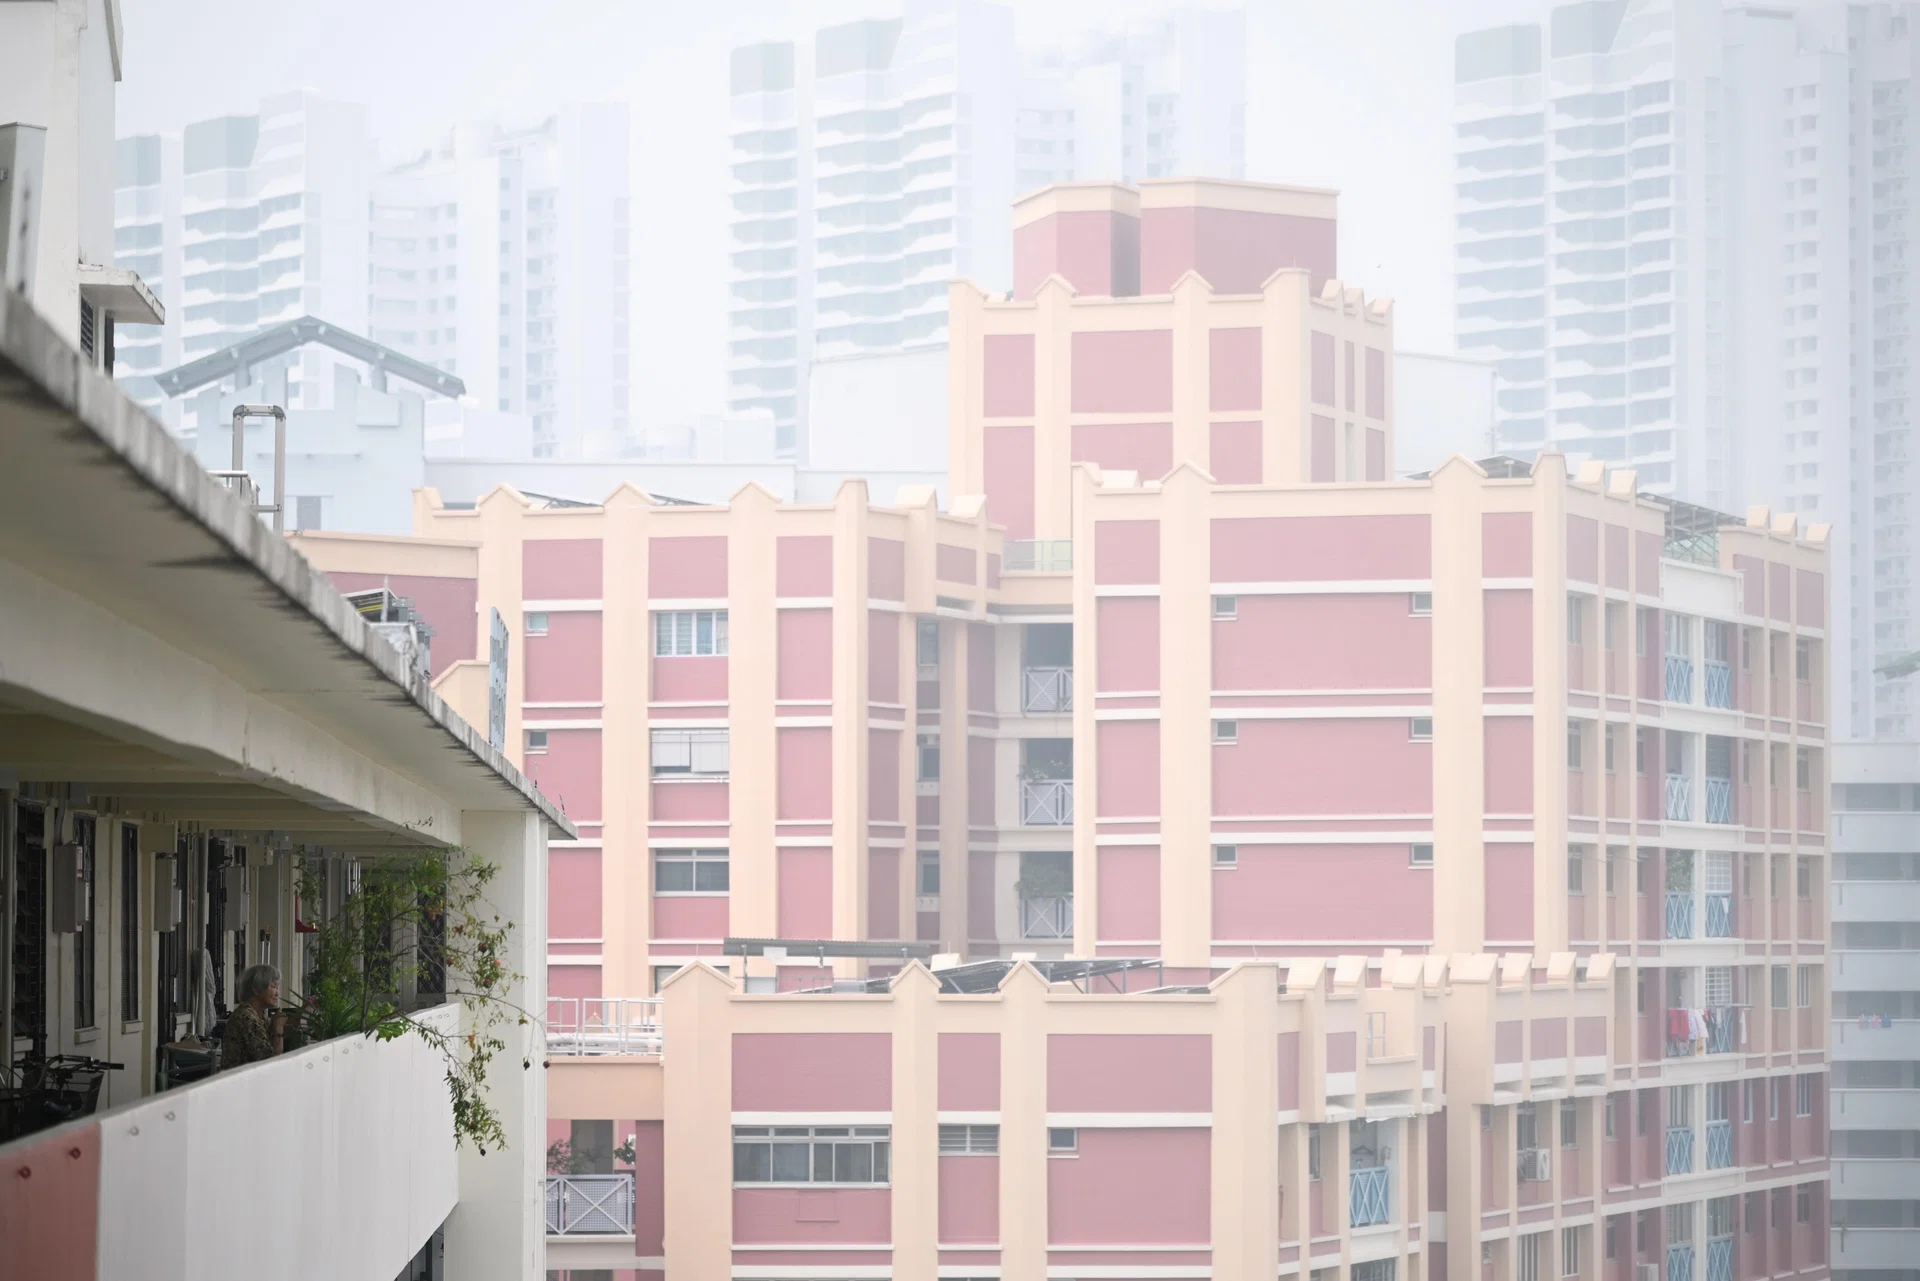
The haze has returned to Singapore, bringing with it a familiar assortment of inconveniences: cancelled outdoor activities, worsening air quality, and the sudden reappearance of N95 masks.
There is also the familiar exchange of diplomatic statements, as Singapore offers assistance and Indonesia struggles to contain fires that have spread across its forests and peatlands.
But beneath the smoke sits a question that rarely receives the same attention as the Pollutant Standards Index. Who owns the land that burns? And perhaps more importantly, who finances the businesses that operate on it?
On 16 October 2026, Singapore’s National Environment Agency (NEA) issued Preventive Measure Notices to seven Indonesian companies under the Transboundary Haze Pollution Act. The agency had identified indications that smoke from fires on their concession land could have travelled to Singapore.
The seven were PT Bumi Andalas Permai, PT Bumi Mekar Hijau, PT Paramitra Mulia Langgeng, PT Sumatera Alam Anugerah, PT SBA Wood Industries, PT Hutan Lestari Raya, and PT Bangkanesia.
The notices require the companies to deploy firefighting personnel, stop or refrain from burning activities, and submit plans to extinguish fires or prevent their recurrence. They do not constitute findings of criminal guilt, and NEA has not established that all seven caused Singapore’s haze.
Nevertheless, the announcement raises a larger issue. Several of these companies have appeared in previous investigations into the corporate structures surrounding one of Indonesia’s biggest industrial groups.
Those investigations suggest that the haze is as much a question of corporate governance as it is of environmental enforcement.
The companies behind the companies
On paper, the seven entities cited by Singapore appear to be standalone Indonesian plantation outfits. In reality, several sit squarely within the orbit of one of Asia’s largest corporate empires: Asia Pulp & Paper (APP), the forestry flagship of the Sinar Mas conglomerate.
Two concessionaires on the NEA’s list — PT Bumi Mekar Hijau and PT Sebangun Bumi Andalas Wood Industries (SBA Wood Industries) — are not new to transboundary haze scrutiny.
Following Indonesia’s catastrophic 2015 fires, APP acknowledged buying wood fibre from both companies, but insisted they were independent, third-party suppliers.
That defense was systematically dismantled in 2018, when Indonesian environmental group Auriga published Removing The Corporate Mask: An Assessment of the Ownership and Management Structures of Asia Pulp & Paper’s Declared Wood Suppliers in Indonesia.
Examining 78 corporate registry filings across 2.6 million hectares of concessions, Auriga found that 24 of the 27 suppliers APP claimed were “independent” shared deep operational ties with Sinar Mas — ranging from overlapping board directors and registered addresses to shared shareholders.
Both Bumi Mekar Hijau and SBA Wood Industries were among them.
That technical distance is where accountability dissolves. A plantation company can retain its own legal identity while maintaining commercial, managerial, or financial relationships with a much larger business network. Such relationships do not automatically establish common ownership or legal responsibility for environmental damage, but they can complicate attempts to determine who exercises effective control.
An investigation must therefore look beyond the names on concession licences. Shareholders, intermediate holding companies, directors, and beneficial owners can all help establish where decisions originate and where responsibility might lie.
Auriga’s findings remain historical evidence rather than confirmation of the companies’ present-day ownership structures. Still, their relevance has resurfaced because two of the companies it scrutinised nearly a decade ago have once again attracted regulatory attention.
The more troubling question is whether the mechanisms available to regulators have kept pace with the complexity of the businesses they seek to regulate.
Follow the money
There is another dimension to the haze that Singapore cannot comfortably regard as an Indonesian problem: finance.
Southeast Asia’s plantation industries require enormous amounts of capital. Companies must acquire and maintain concessions, develop processing facilities, build infrastructure, manage inventories, and finance international trade. These activities connect agricultural businesses to banks, investors, bond markets, and corporate holding structures across multiple jurisdictions.
Singapore’s position as a regional financial centre places it within this ecosystem, even when the underlying industrial activity takes place elsewhere.
A 2019 investigation by Forests & Finance found that 17 corporate groups linked to Indonesia’s forest and peatland fires had received at least US$19.2 billion in corporate loans and underwriting facilities between January 2015 and August 2019.
Singapore-based financial institutions accounted for approximately US$1.4 billion of that financing.
The groups examined included Sinar Mas and Royal Golden Eagle, whose respective pulp and paper operations include Asia Pulp & Paper and APRIL.
This establishes an important point: environmental degradation can sit within business networks supported by international capital, even when financiers have no direct involvement in managing land.
It does not, however, establish that Singapore’s three major banks — DBS, OCBC, and UOB — directly financed the seven concession companies named by NEA. Nor does the available public evidence establish that all seven belong to Singapore-headquartered companies or receive investment from Singapore family offices.
Those allegations require identifiable financial transactions and current corporate ownership records, rather than assumptions based on a group’s regional presence.
Yet the broader financing question is legitimate, especially because Singapore’s banks have already acknowledged that environmental degradation can create material financial risks.
In June 2025, DBS, OCBC, and UOB jointly released a study with the University of Cambridge Institute for Sustainability Leadership, supported by the Monetary Authority of Singapore, examining the financial consequences of nature-related risks.
The banks focused part of their research on palm oil, using hypothetical scenarios involving ecosystem degradation, prolonged drought, and elevated temperatures to examine potential consequences for borrowers and their lenders.
The findings showed that environmental deterioration could affect production and, consequently, creditworthiness. In other words, the banking industry already recognises that environmental damage has financial consequences.
But there is a distinction between treating nature as a source of financial risk to a borrower and examining whether a borrower’s activities contribute to that environmental damage in the first place.
One asks how a bank might lose money. The other asks what responsibilities accompany the money it supplies. For banks betting their reputations on sustainable finance, that discrepancy is becoming difficult to defend.
The uncomfortable business of climate solutions
There is an intriguing parallel developing within Southeast Asia’s climate economy.
On 7 October 2026, barely ten days before NEA announced its action against the seven Indonesian concession companies, venture capital firm East Ventures announced the winners of the fourth Climate Impact Innovations Challenge (CIIC).
Organised with Temasek Foundation and Chinese technology company Tencent, the competition awarded a combined Rp15 billion in catalytic funding to three companies developing environmental technologies.
The recipients were CRecTech, which converts palm oil waste-derived biogas into bio-methanol; Blueyou, which combines mangrove restoration with sustainable aquaculture; and MacroCycle Technologies, which develops textile recycling technology.
Each received Rp5 billion to pilot its solutions in Indonesia.
Among the competition’s investor partners was Sinar Mas Agribusiness & Food, which separately awarded US$50,000 in grant funding to CRecTech. The connection is worth examining.
Sinar Mas Agribusiness & Food forms part of the operations of Golden Agri-Resources, a company listed on the Singapore Exchange. Golden Agri-Resources and APP operate in different sectors of the wider Sinar Mas business network, with distinct corporate structures and management arrangements.
The grant therefore does not mean that APP financed the competition, or that the companies named by NEA contributed to its funding.
Nor does participation in a climate innovation programme necessarily indicate an attempt to obscure environmental controversies. CRecTech’s technology addresses an identifiable industrial challenge, and supporting its development may deliver genuine environmental benefits.
Still, the juxtaposition raises a question that investors, regulators, and consumers should be asking of large conglomerates.
What does environmental responsibility mean when companies associated with the same broader business network pursue different environmental records, priorities, and commitments?
A conglomerate can support low-carbon technology through one business while another associated business faces questions about its land-use practices. The two activities may be legally and operationally distinct. Yet stakeholders increasingly assess corporate groups through their combined economic and environmental influence.
The issue is not whether businesses with complicated environmental histories should participate in climate innovation. Excluding them could deprive promising technologies of funding, industry expertise, and commercial scale.
Rather, it is whether their climate commitments should invite closer examination of the environmental performance of their wider business networks.
Climate philanthropy is comparatively easy to publicise. Responsibility for land use, supplier conduct, and environmental restoration requires a different kind of commitment — one that investors must examine over years rather than at an awards ceremony.
The limits of accountability
Singapore enacted the Transboundary Haze Pollution Act in 2014 to create a legal framework for addressing haze pollution caused by activities beyond its borders.
The legislation allows Singapore to pursue action against entities whose conduct causes or contributes to haze pollution here, subject to its statutory requirements.
But identifying fires on concession land is only part of the challenge. Establishing legal responsibility can require evidence about the origin and movement of smoke, conduct on the ground, contractual arrangements, and the relationship between concession holders and other corporate entities.
Beyond evidentiary hurdles, the THPA has long run up against geopolitical resistance, with Indonesian authorities historically viewing Singapore’s extraterritorial notices as a challenge to national sovereignty.
The latest NEA notices demonstrate the government’s willingness to use its regulatory powers. Whether they eventually produce findings of liability remains to be seen.
For businesses, however, legal enforcement represents only one form of accountability.
Banks can examine how their clients manage environmental risks. Institutional investors can demand greater transparency over ownership and operations. Companies can strengthen supplier oversight, while boards can assess whether environmental commitments translate into measurable performance throughout their businesses.
These mechanisms do not depend entirely on governments proving violations in court. They depend on the willingness of corporate decision-makers to ask harder questions before committing capital, and to act when evidence identifies unacceptable risks.
There are limits to what public information currently establishes about the seven companies. Historical ownership investigations cannot substitute for current beneficial ownership records, and relationships within a diversified business group cannot automatically establish liability across separate legal entities.
Precision here is legally non-negotiable. Yet those very corporate firewalls expose the central dilemma: how to trace accountability through shell structures engineered specifically to resist tracing.
But they also expose the difficulty facing anyone attempting to understand where economic responsibility for environmental damage begins and ends. A company’s legal boundaries may be clear on paper. Its commercial relationships can be considerably more complicated.
When the smoke clears
Singapore has spent considerable effort establishing itself as a centre for sustainable finance, attracting capital for decarbonisation, environmental technologies, and the transition towards a lower-carbon economy.
These ambitions deserve serious consideration, as do the investments already supporting climate innovation across the region.
But sustainable finance cannot concern itself exclusively with capital flowing towards environmental solutions. It must also confront the environmental consequences of existing economic activity.
The recurring haze is a particularly visible reminder of those consequences.
It moves across national boundaries, disrupts ordinary life, and imposes costs on people who may have little connection to the businesses operating on the land where fires occur.
The capital supporting those businesses can cross borders just as readily, although its movements are considerably harder for the public to observe.
None of this means Singapore’s financial institutions should bear responsibility for every fire in Indonesia, or that every corporate connection creates culpability. It means that ownership, financing, and environmental performance deserve to be examined together, especially where companies operate in industries exposed to significant ecological risks.
The question for Singapore, then, extends beyond how effectively it can identify and pursue companies associated with transboundary haze.
It is whether its financial institutions, investors, and corporate leaders are prepared to apply the same scrutiny to the economic relationships that sustain the region’s plantation industries.
After all, the smoke eventually disperses. The money does not.